
Diwali Bonus 2026: Official 8.33% to 20% Calculation Formula Under Payment of Bonus Act (Why the ₹7,000 Ceiling Caps Your Payout)
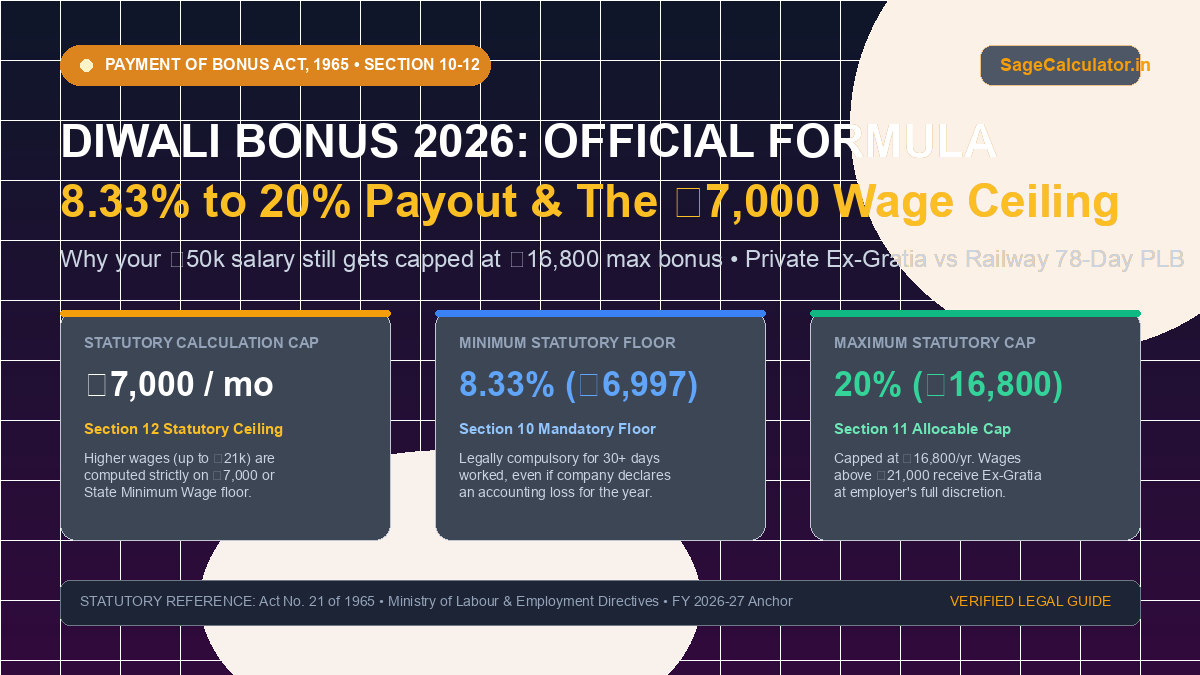
- Statutory eligibility ceiling under Section 2(13) is ₹21,000 per month (Basic Pay + Dearness Allowance).
- Statutory calculation ceiling under Section 12 is capped at ₹7,000 per month or the State Minimum Wage, whichever is higher.
- Section 10 guarantees an absolute minimum floor of 8.33% (₹6,997 annually) even if the establishment suffers financial losses.
- Section 11 caps the maximum statutory bonus at 20% (₹16,800 annually) based on allocable surplus under Section 15.
- Employees earning above ₹21,000 monthly basic are not covered by the Act; payouts are discretionary Ex-Gratia and 100% taxable under Section 17(1).
Calculate Your Exact Diwali Bonus & Ex-Gratia Payout
Simulate your 8.33% to 20% statutory bonus against the ₹7,000 wage ceiling, pro-rata days worked, and ex-gratia tax deductions.
The October Paycheck Dilemma: Why Your Bonus Falls Short of Expectations
With Diwali and Dhanteras festivities underway across India in late October 2026, millions of private-sector, factory, logistics, and IT professionals eagerly inspect their monthly salary slips for the festive bonus.
For many corporate professionals earning ₹50,000 or ₹1,00,000 per month, the actual credited amount often triggers immediate confusion: why is the festive bonus capped at exactly ₹6,997 or ₹16,800 rather than a percentage of their full monthly remuneration?
The answer lies in the statutory architecture of the Payment of Bonus Act, 1965 (Act No. 21 of 1965). Indian labour laws strictly distinguish between mandatory Statutory Bonus (governed by parliamentary statute) and discretionary Ex-Gratia or Performance Incentives (granted solely at corporate management discretion).
The Two Statutory Ceilings: Eligibility vs Calculation Cap
To understand your Diwali bonus slip, you must separate two statutory wage caps defined under the Act:
1. The Eligibility Ceiling (Section 2(13)): Any employee drawing Basic Pay + Dearness Allowance up to ₹21,000 per month who has worked for at least 30 working days in the accounting financial year is legally entitled to receive a statutory bonus.
2. The Calculation Ceiling (Section 12): Even if your Basic Pay is ₹18,000 or ₹20,000 per month, the bonus is NOT computed on your actual salary. Section 12 mandates that bonus calculations must be strictly pegged to ₹7,000 per month (or the scheduled minimum wage for your employment category fixed by the appropriate State Government, whichever is higher).
| Monthly Basic + DA | Calculation Base (Per Month) | Minimum Bonus (8.33% Floor) | Maximum Bonus (20.00% Cap) | Legal Status under 1965 Act |
|---|---|---|---|---|
| ₹6,000 / month | ₹6,000 (Actual Salary) | ₹5,998 / year | ₹14,400 / year | Mandatory Statutory Bonus |
| ₹7,000 / month | ₹7,000 (Exact Ceiling) | ₹6,997 / year | ₹16,800 / year | Mandatory Statutory Bonus |
| ₹12,000 / month | ₹7,000 (Statutory Cap) | ₹6,997 / year | ₹16,800 / year | Mandatory Statutory Bonus |
| ₹20,000 / month | ₹7,000 (Statutory Cap) | ₹6,997 / year | ₹16,800 / year | Mandatory Statutory Bonus |
| ₹21,000 / month | ₹7,000 (Statutory Cap) | ₹6,997 / year | ₹16,800 / year | Statutory Upper Eligibility Cutoff |
| ₹35,000+ / month | Outside Act (Not Applicable) | Discretionary Ex-Gratia | Discretionary Ex-Gratia | Ex-Gratia / Management Discretion |
How the 8.33% Minimum Floor and 20% Maximum Cap Function
Under the statutory guidelines, an establishment cannot randomly choose an arbitrary bonus figure. The payout is strictly bound by statutory boundary conditions:
• Section 10 (Mandatory 8.33% Floor): Every covered establishment must pay a minimum bonus of 8.33% of the calculated wage, or ₹100, whichever is higher. Crucially, this 8.33% payment is legally binding even if the company declared an accounting loss during the financial year.
For an employee capped at the ₹7,000 calculation base, the minimum annual statutory bonus equals: ₹7,000 × 8.33% × 12 months = ₹6,997.20 (statutorily rounded to ₹6,997).
• Section 11 (Maximum 20% Allocable Cap): If the enterprise generates an "allocable surplus" (computed after statutory deductions, depreciation, and tax reserves under Section 4 and the Third Schedule), the employer must distribute higher bonus proportions up to a strict ceiling of 20%.
For the ₹7,000 calculation base, the maximum annual statutory bonus equals: ₹7,000 × 20% × 12 months = ₹16,800.
Pro-Rata Adjustments for Partial Service and Leave Deductions
If an employee joined mid-year or had unpaid leave / loss of pay (LOP) days, the statutory bonus is adjusted strictly pro-rata according to actual days worked:
• Minimum Service Condition: An employee must complete at least 30 working days in the financial year to become eligible under Section 8.
• Pro-Rata Formula: If an eligible employee with a ₹7,000 wage base worked 210 days in a standard 365-day accounting year with a 10% declared bonus, the statutory payout equals: (210 ÷ 365) × (₹7,000 × 10% × 12) = ₹4,833.
• Disqualification Grounds: Under Section 9 of the Act, an employee forfeits all statutory bonus rights if dismissed from service for fraud, riotous or violent behaviour on the establishment premises, or theft, misappropriation, or sabotage of employer property.
Central Government Bonus: Railway 78-Day PLB vs Non-PLB Ad-Hoc Bonus
For Central Government employees, festive bonus announcements operate under specialized Cabinet-approved productivity frameworks rather than the private-sector Payment of Bonus Act:
• Indian Railways 78-Day Productivity Linked Bonus (PLB): Approved for over 11.7 lakh non-gazetted railway personnel ahead of the festive season. The calculation uses the ₹7,000 monthly wage ceiling: (₹7,000 ÷ 30 days) × 78 days = ₹17,951 per eligible employee.
• Non-PLB Ad-Hoc Bonus for Central Staff: Non-gazetted employees in central departments (paramilitary forces, postal staff, civil accounts) receive an ad-hoc festive bonus equivalent to 30 days emoluments computed on the ₹7,000 ceiling: (₹7,000 ÷ 30.4 days) × 30 days = ₹6,908.
Income Tax Treatment: Is Your Diwali Bonus Tax-Free?
A pervasive workplace myth assumes festive bonuses carry tax exemptions under Section 10 of the Income Tax Act. This is incorrect.
Both statutory bonus and discretionary ex-gratia are treated as "Profits in lieu of salary" under Section 17(1)(iv) of the Income Tax Act, 1961. The entire bonus amount is added to your gross taxable salary for FY 2026-27 (AY 2027-28).
Your employer will deduct Tax Deducted at Source (TDS) under Section 192 based on your applicable income tax slab under either the New Tax Regime (Section 115BAC) or Old Tax Regime. For employees in the 20% or 30% brackets, TDS withholding directly reduces net in-hand festival bonus proceeds.
Frequently Asked Questions (FAQs)
Is Diwali bonus mandatory for all private sector companies in India?▼
Yes, if the establishment employs 20 or more persons on any day during the accounting financial year (or 10 or more in states where the threshold is reduced). Every employee drawing Basic + DA up to ₹21,000 per month who has worked for at least 30 working days is legally entitled to a statutory bonus.
What if my basic salary is ₹35,000 per month—am I legally entitled to statutory bonus?▼
No. Employees earning Basic + DA above ₹21,000 per month fall outside the mandatory provisions of the Payment of Bonus Act, 1965. Any festive payout granted by your employer is classified as discretionary Ex-Gratia or Performance Bonus.
Can an employer pay less than 8.33% if the company suffered a severe financial loss?▼
No. Under Section 10 of the Act, paying the minimum bonus of 8.33% (or ₹100, whichever is higher) is an unconditional statutory obligation. Financial losses do not exempt covered employers from this minimum floor.
What is the exact maximum statutory Diwali bonus an employee can receive under the Act?▼
Under Section 11 and Section 12, the maximum statutory bonus is 20% of the calculated wage. With the calculation ceiling capped at ₹7,000 per month, the maximum statutory bonus is ₹16,800 per year (₹7,000 × 20% × 12).
Is Diwali bonus subject to PF and ESI statutory deductions?▼
Annual statutory bonus paid under the Payment of Bonus Act does not attract Provident Fund (EPF) deductions under Section 2(b) of the EPF Act. However, if bonus is disbursed monthly as an allowance, EPFO treatment differs. Statutory bonus is also exempt from ESI contribution computations.