
Paying Over ₹50,000 Rent? Slashed 2% TDS Rule Takes Effect, But Landlord’s Inoperative PAN Can Trigger 20% Penal Tax
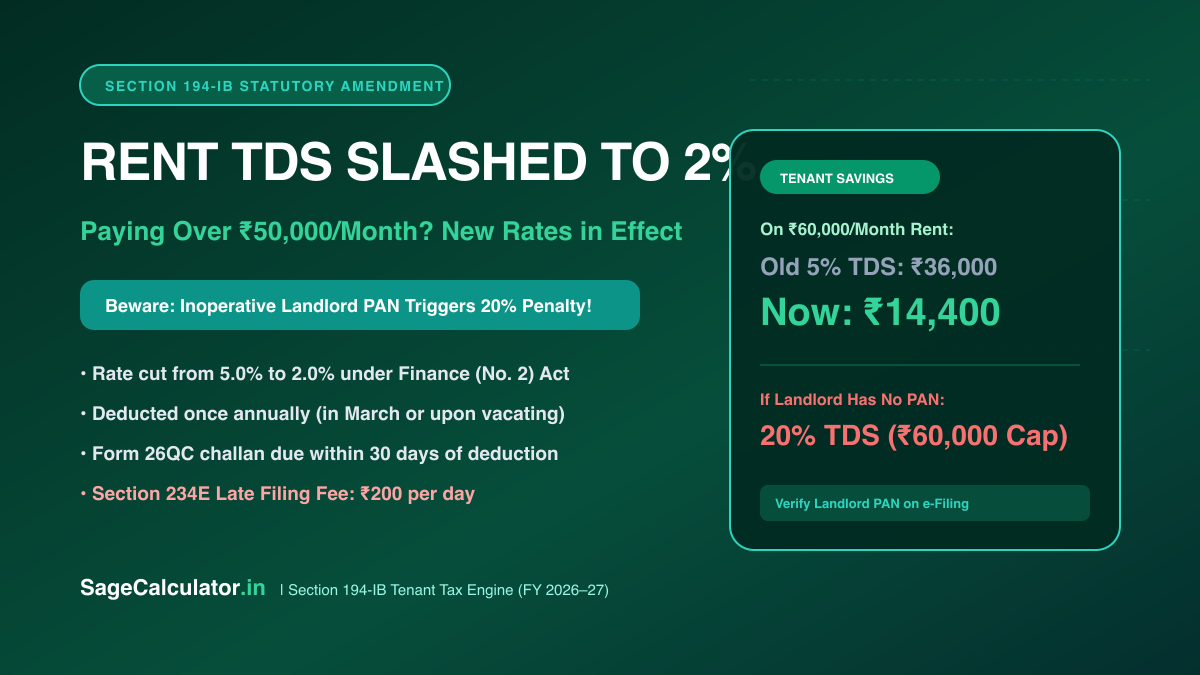
- Statutory tenant TDS rate under Section 194-IB slashed from 5% to 2% w.e.f. October 1, 2024 (Finance (No. 2) Act).
- Applies to Individuals and HUFs paying monthly rent exceeding ₹50,000 (rent up to ₹50k is 100% exempt).
- TDS is deducted only once per year—in March or in the month when vacating the rented property.
- Under Section 206AA, if the landlord has an invalid or inoperative PAN, the TDS rate jumps tenfold to 20%, strictly capped at one month’s rent.
Calculate Your Section 194-IB Tenant TDS & Form 26QC Deadlines
Audit monthly rent, compare 2% vs legacy 5% deductions, check late fees (₹200/day), and calculate landlord net rent.
Welcome Relief for High-Rent Tenants in Bengaluru, Mumbai and Delhi-NCR
In major metropolitan tech corridors where gated-community 3BHK rents routinely range from ₹60,000 to ₹1,20,000 per month, statutory tenant TDS compliance under Section 194-IB has long been a source of paperwork friction.
Under the revised provisions of the Income Tax Act, the central government has slashed the TDS deduction rate from 5% down to 2%, reducing the upfront cash withheld from landlords and streamlining annual compliance.
When Must the 2% TDS Be Deducted and Remitted?
A frequent error made by tenants is deducting TDS every single month. By law, Section 194-IB does NOT require monthly withholding:
• Deduction Window: TDS must be deducted only once in the financial year—specifically from the rent payment of March (the last month of the financial year), or in the final month of the tenancy if the tenant vacates earlier.
• Payment Challan: The tenant must deposit the withheld tax with the central government using challan-cum-statement Form 26QC within 30 days from the end of the month in which deduction was made (e.g., April 30 for March deductions).
• Certificate to Landlord: Within 15 days of Form 26QC submission, the tenant must download and furnish Form 16C TDS certificate to the landlord.
| Metric | Legacy 5% TDS Rule | Current Slashed 2% Rate | Net Cashflow Impact |
|---|---|---|---|
| Monthly Rent | ₹75,000 | ₹75,000 | No change |
| Annual Rent Paid | ₹9,00,000 | ₹9,00,000 | No change |
| Total Annual TDS | ₹45,000 (5%) | ₹18,000 (2%) | ₹27,000 Savings |
| March Net Rent Paid to Landlord | ₹30,000 | ₹57,000 | Landlord receives +₹27,000 cash |
The 20% Penal Trap: Section 206AA and Landlord PAN Validity
Tenants must exercise extreme vigilance regarding their landlord’s PAN status. If the landlord fails to furnish a valid PAN, or if their PAN has become "inoperative" due to non-linkage with Aadhaar, Section 206AA mandates a punitive TDS rate of 20% instead of 2%!
However, the law incorporates a vital protective safeguard under Section 194-IB(4): penal tax cannot exceed the rent payable for the last month of the tenancy. A tenant cannot be forced to pay penal tax out of their own personal pocket.
Frequently Asked Questions (FAQs)
Do I need a TAN (Tax Deduction Account Number) to deduct Section 194-IB TDS?▼
No. Individuals and HUFs are specifically exempt from obtaining a TAN. All filings and challans are executed using the tenant’s standard PAN on the Protean / Income Tax e-Filing portal.
What is the late fee for missing the Form 26QC filing deadline?▼
Under Section 234E, a late filing fee of ₹200 per day is levied for every day the default continues, capped at the total amount of TDS deducted. Delayed remittance also attracts 1.5% per month interest under Section 201(1A).
If two roommates pay ₹35,000 each (total ₹70,000), does TDS apply?▼
If the lease agreement explicitly specifies individual co-tenants and their separate liability is ₹35,000 each (below the ₹50,000 statutory threshold), Section 194-IB TDS does not apply.